ProfSteveKeen
38 minutes
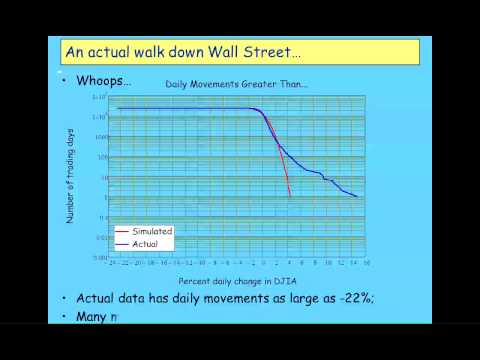
Stock market dynamics deviate from the Efficient Market Hypothesis and the Gaussian normal distribution due to nonlinear feedback mechanisms characteristic of non-equilibrium systems. The core theoretical mechanism is defined by a Power Law probability distribution, where the frequency of extreme events scales as $x^{-\alpha}$, validating that large deviations are not vanishingly rare anomalies but intrinsic behaviors of self-referential markets. This framework belongs to behavioral finance and chaos theory, specifically replacing deterministic equilibrium models with non-equilibrium descriptions based on coupled differential equations.